Buying · Maine
Mortgage Preapproval in Maine: A Buyer’s Guide
How Maine buyers can prepare for mortgage preapproval, compare total monthly costs and protect their approval while shopping for a home.
A mortgage preapproval helps define a realistic home-search budget and demonstrates that a lender has reviewed specified financial information. It is not a final loan commitment, and it does not replace property approval, appraisal, title, insurance or updated underwriting.
Prequalification versus preapproval
Terminology varies by lender. Ask what documents and credit review support the letter, how long it remains current and what conditions remain.
Information lenders commonly request
- income and employment documentation;
- bank, investment and asset statements;
- debt and housing obligations;
- identification and credit authorization; and
- information about down-payment and closing-cost funds.
Compare total payment, not only price
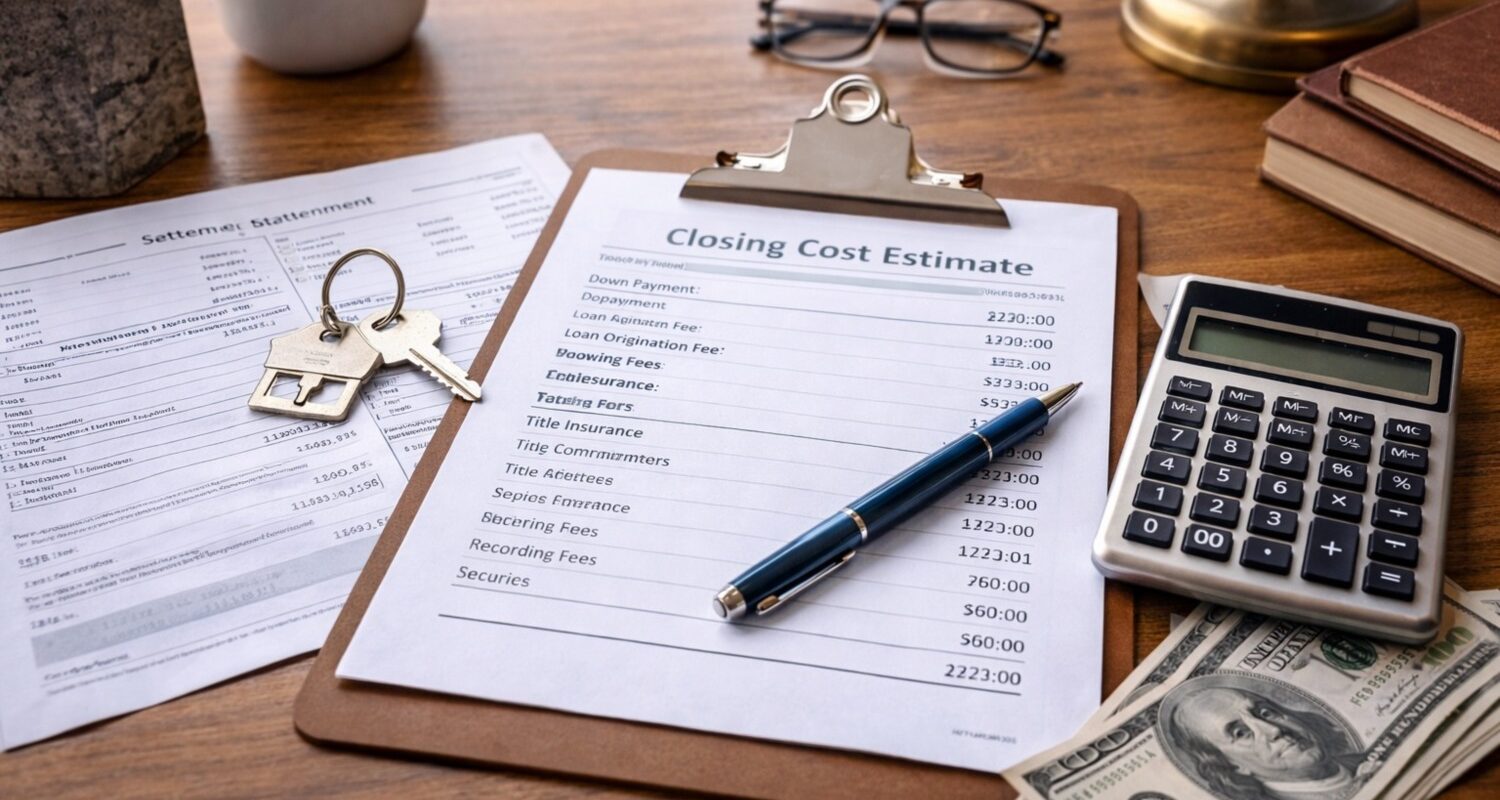
Review principal, interest, property taxes, homeowners or condo insurance, mortgage insurance, association fees and expected utilities. Maine heating and private-system costs can materially affect household affordability even when they are outside lender ratios.
Match financing to property type
Condominiums, multifamily homes, manufactured housing, investment property, seasonal homes, new construction and properties needing repairs may require different loan programs and project review. Tell the lender what you intend to buy before making an offer.
Protect the approval during the search
Avoid new debt, major account transfers, job changes or large undocumented deposits without discussing them with the lender. Provide updated documents promptly and maintain funds for inspections, closing and reserves.
Frequently asked questions
Does preapproval guarantee financing?
No. Final approval depends on updated borrower information and the property, appraisal, title, insurance and program requirements.
Will shopping lenders affect credit?
Credit-scoring treatment depends on timing and model. Ask lenders how inquiries will be handled and compare written loan estimates.
Should I use the maximum approval amount?
Not necessarily. Set a comfortable budget using total ownership cost and other financial goals.
Begin a Maine home search
Bean Group can coordinate your search with a qualified lender and property-specific due diligence. Contact Bean Group to begin.
This guide is general information, not lending or financial advice. Loan terms and eligibility vary.